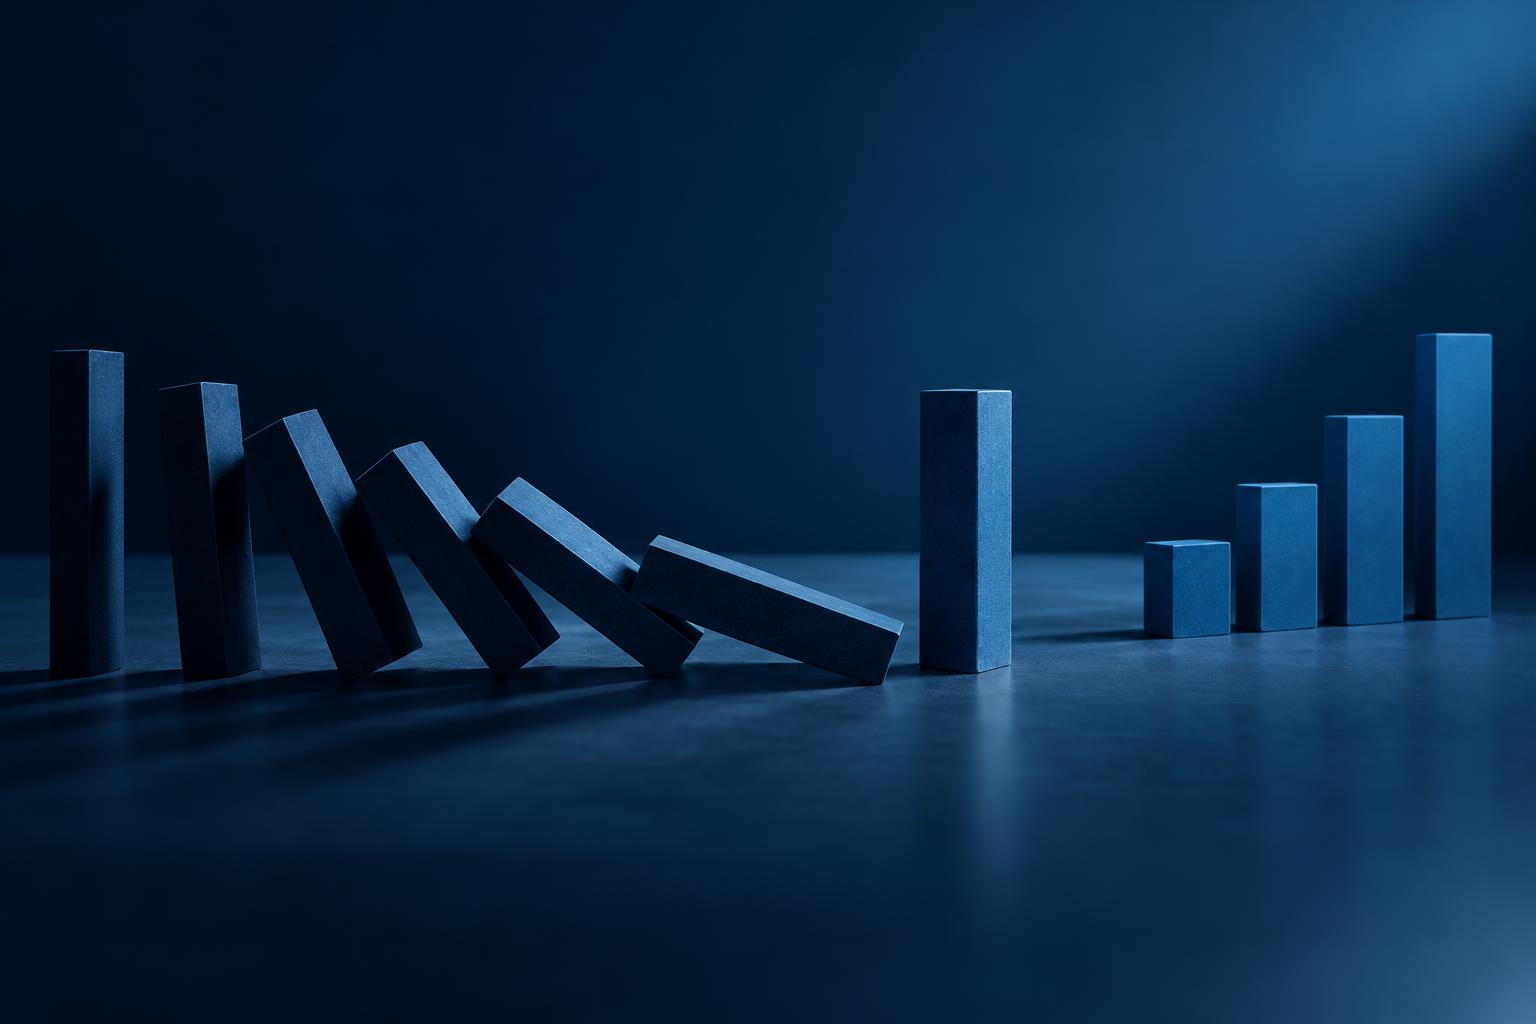
Economic downturns and financial crises are often driven as much by psychology as by actual economic conditions. When consumers and businesses lose confidence, their defensive actions can accelerate a recession, just as fear can trigger a bank run. In both cases, perception—rather than reality alone—can drive destructive economic behaviors. However, just as negative sentiment can spiral into crisis, proactive measures can restore confidence and prevent economic collapse.
How Consumer and Business Perceptions Drive a Recession
A recession typically begins when economic activity slows, but it is often prolonged or deepened by fear-driven behaviors. Here’s how perception plays a critical role:
1. Declining Consumer Confidence
Consumers are the backbone of the economy, and their confidence in future financial stability influences spending habits. If people fear a recession—whether due to job market concerns, declining stock values, or media pessimism—they often cut back on discretionary spending. This reduction in spending weakens businesses, leading to revenue declines and job losses, which further reinforce the downturn.
2. Business Uncertainty Leads to Reduced Investment
Business leaders react to perceived risks in much the same way as consumers. If they anticipate a slowdown, they may freeze hiring, delay expansion plans, and cut costs to preserve cash. These actions, while individually rational, collectively contribute to slower economic growth and increased unemployment.
3. Market and Credit Contractions
Investor sentiment also plays a key role. When uncertainty dominates financial markets, stock values fall, reducing household wealth and further dampening consumer spending. Meanwhile, banks and lenders become more cautious, tightening credit availability, making it harder for businesses and individuals to borrow, which slows economic growth further.
4. Media and Narrative Amplification
News reports focusing on economic decline, layoffs, and financial instability can heighten public fear. When pessimism dominates headlines, people react by making conservative financial choices—often reinforcing the downturn they feared.
How Perceptions Lead to a Bank Run
A bank run is a more extreme and immediate example of how perception shapes economic behavior. Unlike recessions, which develop over time, a bank run can unfold within hours or days, fueled entirely by fear and mistrust.
1. Fear of Insolvency Creates Panic
Banks operate on fractional reserve banking, meaning they don’t hold all depositors' money at once. If depositors believe a bank is failing—whether due to rumors, financial distress, or a previous banking collapse—they rush to withdraw their funds.
2. The Self-Fulfilling Prophecy
Even if a bank is financially stable, a surge of withdrawals can deplete its reserves, forcing it to sell assets quickly at a loss. This can lead to actual insolvency, fulfilling the very fears that caused the panic.
3. Contagion Effect Spreads to Other Banks
If one bank experiences a run, depositors at other banks may fear a similar fate and withdraw their funds preemptively. This systemic fear can trigger widespread financial instability.
How to Reverse Negative Perceptions
The same psychological forces that drive fear-based economic behavior can also be harnessed to restore confidence and stability. Here’s how:
1. Government and Central Bank Action
In a recession, governments can implement stimulus measures, such as tax cuts, infrastructure spending, and monetary easing, to encourage spending and investment.
During a bank run, central banks can provide emergency liquidity to struggling banks to prevent collapse and reassure depositors.
2. Transparency and Communication
In both recessions and bank crises, strong leadership and clear messaging are essential. Governments, businesses, and financial institutions must proactively communicate stability, ensuring that consumers and businesses don’t overreact to perceived threats.
The FDIC’s guarantee of bank deposits, for example, reassures people that their money is safe, reducing panic-driven withdrawals.
3. Confidence-Boosting Measures
Businesses increasing hiring and investment signals confidence, encouraging consumers to spend.
Banks limiting withdrawal limits or temporarily closing to stop panic-driven runs can help stem financial collapse.
4. Shifting Media Narratives
Encouraging balanced reporting and highlighting economic resilience can help counteract doom-and-gloom narratives.
Thoughtful economic messaging from business leaders, economists, and policymakers can help shift sentiment toward recovery.
Conclusion
Whether through a slow-burning recession or a sudden bank run, negative perceptions can have real economic consequences. While financial fundamentals play a role, it is often consumer and business sentiment that determines the severity of a downturn. By recognizing the power of perception and actively working to restore confidence, leaders can help mitigate economic crises and accelerate recovery.